




Ecommerce bookkeeping involves more than recording money that enters and leaves a bank account. Online sellers must reconcile orders, marketplace settlements and payment-processor payouts while separately recording fees, refunds, chargebacks, inventory costs and VAT.
The amount deposited by Amazon, Shopify, eBay, Etsy, Stripe or PayPal will often be lower than the value of the underlying sales. Recording only the net deposit can understate both revenue and expenses, distort profit margins and lead to incorrect VAT reporting.
This guide explains how UK ecommerce businesses can organise their bookkeeping, reconcile sales channels, account for inventory and prepare reliable financial information.
What is Ecommerce Bookkeeping?
Ecommerce bookkeeping is the process of recording, categorising and reconciling the financial transactions of an online business.
Unlike simpler service businesses, ecommerce sellers may receive thousands of orders through multiple platforms while receiving only a small number of combined payouts. Their records must connect gross sales with marketplace fees, payment-processing charges, refunds, chargebacks, fulfilment costs, VAT and the amount eventually deposited into the bank.
The five principal account categories are:
- Assets: Resources controlled by the business, including cash, inventory, payment-processor balances and amounts owed by customers.
- Liabilities: Amounts the business owes, such as supplier bills, loans, taxes and VAT due.
- Revenue: Income earned from selling goods or services before fees and other deductions.
- Expenses: Costs incurred while operating the business, including advertising, software, professional fees and marketplace charges.
- Equity: The owner’s residual interest after liabilities are deducted from assets, including share capital and retained earnings.
Transactions are organised into accounts within the general ledger. A well-designed chart of accounts helps an ecommerce business distinguish sales, fees, inventory, COGS, refunds and other important figures.
Learn what bookkeeping is, bookkeeping terminology, and how poor bookkeeping is likely to hurt your business in these guides.
Why Bookkeeping Matters for Ecommerce Businesses
Accurate bookkeeping allows an ecommerce business to:
- Understand profitability by product and sales channel
- Monitor cash held by marketplaces and payment processors
- Plan supplier, payroll and tax payments
- Track inventory and calculate COGS
- Identify rising fees, refunds or chargebacks
- Prepare reliable VAT returns and year-end accounts
- Forecast cash requirements and plan for growth
These benefits depend on recording gross sales and the related deductions correctly, rather than treating net marketplace payouts as revenue.
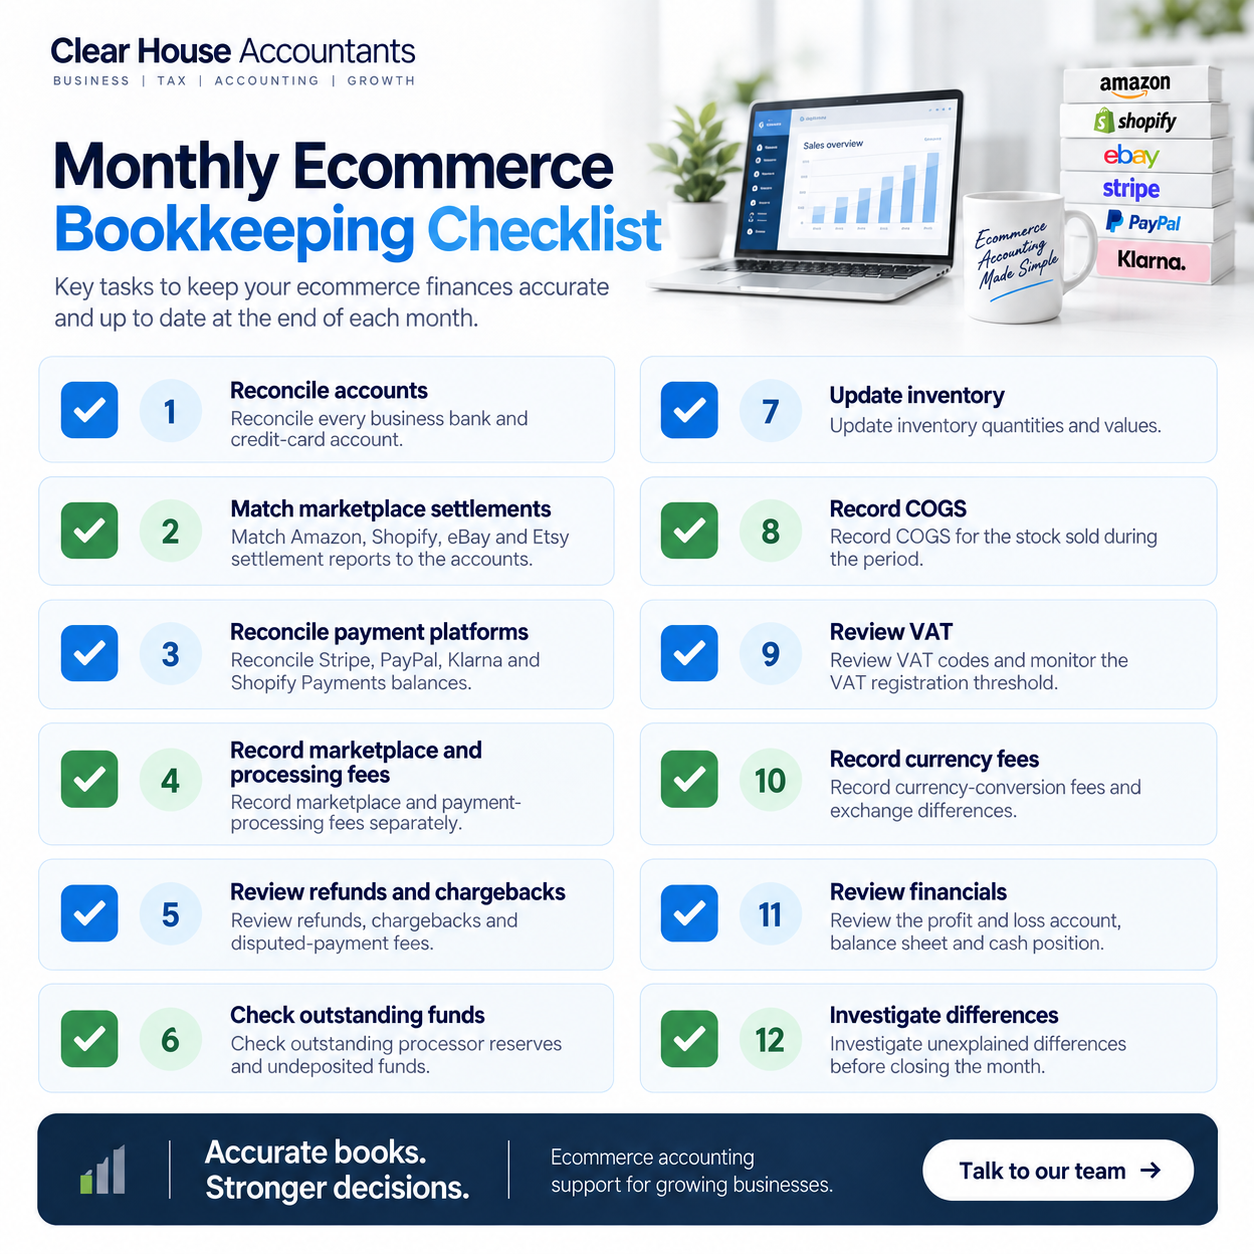
Monthly Ecommerce Bookkeeping Checklist
At the end of each month:
How to Set Up Bookkeeping for Your Ecommerce Business
Follow these steps to set up bookkeeping for your ecommerce business:
Separate Your Business and Personal Finances
It is challenging to keep track of your income and expenses when your finances are mixed up. A separate business account makes it simple to track your transactions, generate financial reports, and calculate your tax deductions.
Choosing the wrong setup can complicate your ecommerce finances and reporting as you grow. Learn how to choose the right setup in this guide.
Use a Double-Entry Bookkeeping System
Double-entry bookkeeping records both sides of every transaction. For example, purchasing inventory increases the inventory asset while reducing cash or creating an amount payable to the supplier.
This approach makes it possible to produce a reliable profit and loss account and balance sheet. It is normally the appropriate system for limited companies and ecommerce businesses managing inventory, VAT, multiple currencies or several sales channels.
Single-entry records may be adequate in limited, straightforward circumstances, but they provide less control and are unlikely to support a growing multi-channel ecommerce business.
Create a Chart of Accounts
A general ledger keeps track of your financial transactions. It makes finding transactions simple without having to sift through your bank and credit card statements. It can be further divided into sub-ledgers for transactions involving assets, liabilities, equity, revenue, and expenses.
If you are just starting, you should learn how to get your chart of accounts right in our detailed guide.
Record Every Transaction
Record every ecommerce transaction rather than only the final amount received in your bank account. Amazon settlements, Shopify payouts and payments from eBay or Etsy may combine gross sales with marketplace fees, commissions, refunds and other deductions. Separating these amounts and reconciling them against marketplace reports and bank deposits helps keep revenue and expenses accurate. HMRC requires limited companies to keep records for six years from the end of the accounting period.
It is important to remember that adding your net cash amount deposited by these platforms directly to your total revenue can distort profit margins.
Sole traders and partnerships must keep records for five years from the 31 January self-assessment deadline.
Consistent Monitoring
Maintaining consistent and continuous attention to bookkeeping makes it easier. Reconcile transactions regularly and review your accounts at appropriate intervals based on the size and complexity of your business.
This habit keeps your funds organised and enables you to identify mistakes early on. Creating financial reports such as income statements, balance sheets, and cash flow statements every month and every quarter helps track the development and trends of your business.
How to Reconcile Ecommerce Sales Channels
Amazon settlements, Shopify payouts and payments from eBay or Etsy should be reconciled with the underlying platform reports and the deposits shown on the business bank account.
Do not record the net payout as total sales. A settlement may contain:
- Gross product sales
- Shipping income
- VAT or other taxes
- Discounts
- Customer refunds
- Marketplace commissions
- Fulfilment and storage fees
- Advertising costs
- Reserves or withheld balances
- Currency-conversion adjustments
For example:
- Gross sales: £10,000
- Less customer refunds: £500
- Less marketplace fees: £1,200
- Less fulfilment and advertising costs: £600
- Less reserve adjustment: £200
- Net bank payout: £7,500
The bookkeeping records should show £10,000 of gross sales and each deduction separately. The resulting £7,500 should then reconcile with the bank deposit.
This provides a more accurate view of revenue, operating costs, VAT and profitability by sales channel.
Seven Tips for Ecommerce Bookkeeping
These are some tips for effective ecommerce bookkeeping for your business:
1. Choose the Right Accounting Software
Accounting software such as Xero or QuickBooks maintains the business’s general ledger and financial reports. Ecommerce connector software performs a different function: it imports or summarises transactions from marketplaces and payment platforms before posting them to the accounting system.
When choosing software, consider:
- Supported marketplaces and payment processors
- VAT and multi-currency functionality
- Inventory integrations
- Settlement-level reconciliation
- Treatment of refunds, fees and reserves
- Transaction volume and subscription cost
- Access for the business’s bookkeeper or accountant
Explore the available options in our guide to cloud accounting software for small businesses.
2. Reconcile Payment Processors
Payment processors should normally be treated as separate financial accounts rather than extensions of the bank account.
A Stripe, PayPal, Klarna or Shopify Payments balance may contain customer receipts that have not yet reached the bank. It may also include processing fees, refunds, chargebacks, reserves and currency adjustments.
For each payout:
- Match the underlying customer transactions to the processor report.
- Record gross sales rather than only the net deposit.
- Record fees, refunds and chargebacks separately.
- Account for any balance retained by the processor.
- Match the final payout to the bank deposit.
This explains timing differences and prevents sales from being duplicated or understated.
Businesses should also prepare a regular cash-flow forecast to anticipate supplier, tax and operating payments.
3. Understand Your Cost of Goods Sold (COGS)
Inventory is normally recorded as an asset when it is purchased. Its cost is transferred to cost of goods sold when the corresponding product is sold.
A simplified calculation is:
Opening inventory + purchases and landed costs − closing inventory = cost of goods sold
Depending on the circumstances, landed inventory cost may include the supplier price, inbound freight, customs duty and other costs required to bring the stock to its present location and condition.
Outbound delivery, marketplace commissions, advertising and fulfilment fees are generally tracked separately from product cost. This helps the business understand both gross margin and contribution margin.
Returns, damaged products, missing inventory and stock held by fulfilment providers should also be reflected in the inventory records.
Learn how a profit and loss account can help you monitor profitability in this guide.
4. Calculate Your Break-Even Point
When sales equal expenses, a business reaches its break-even point. To calculate it, you need:
- Fixed costs
- Variable expenses
- The retail price of the item
Fixed costs are ongoing expenses that remain the same regardless of how many sales you make, such as rent and insurance. Variable costs fluctuate depending on revenue levels and may include direct materials and direct labour.
The break-even point is determined by dividing your total fixed costs by the difference between your unit selling price and your variable cost per unit.
Formula:
Break-Even Units = Fixed Costs divided by (Selling Price minus Variable Cost per Unit).
This formula is most useful for a business selling one product. A multi-product ecommerce business may need to calculate break-even revenue using its overall or weighted average contribution margin because products can have different prices, fees and variable costs.
5. Keep All Necessary Records
A significant part of bookkeeping involves maintaining and organising data. For example, if a tax authority requests details regarding particular transactions made three years ago, you can present your materials immediately because they are already well-organised.
Suitable accounting and document-management software can help retain invoices, receipts, marketplace reports and payment records. Businesses that need assistance choosing or maintaining their system can consult a provider of professional bookkeeping services.
6. Inventory Management
A reliable inventory management system is essential for your ecommerce business, both when reviewing your COGS as a whole and at a more detailed product level. You need precise inventory-level information to properly record your COGS. It is crucial for both tax purposes and better decision-making.
7. Prepare Your Financial Statements
Maintaining accurate and up-to-date financial records is necessary to anticipate major issues before they arise. The three key statements every ecommerce business should make regularly are:
- Income Statement: tracks revenue and expenses over a period
- Balance Sheet: shows assets, liabilities, and equity at a point in time
- Cash Flow Statement: tracks the movement of cash in and out of the business
Explore what a balance sheet or statement of financial position is and how it works in this guide.
How to Record Refunds and Chargebacks
Refunds and chargebacks should not be combined with ordinary marketplace fees.
A refund reverses all or part of a previously recorded sale. The business may also need to adjust the associated VAT and return the product to inventory if it is received in a saleable condition.
A chargeback occurs when a customer disputes a payment. It may include both the disputed sales amount and an additional processor fee. Recording that fee separately makes it easier to measure the cost of disputes.
Reviewing refunds and chargebacks by product and sales channel can reveal fulfilment problems, misleading listings, product-quality issues or unusually high fraud levels.
UK VAT and Making Tax Digital for Ecommerce Businesses
UK businesses must normally register for VAT when VAT-taxable turnover exceeds £90,000 over a rolling 12-month period. Registration may also be required when a business expects taxable turnover to exceed £90,000 within the next 30 days.
Ecommerce businesses should monitor gross taxable sales rather than net marketplace payouts when checking the threshold.
VAT can become more complex when a business imports goods, holds stock in another country, sells to EU consumers, uses overseas fulfilment centres or incurs marketplace fees from overseas suppliers. Depending on the sales model, import VAT, postponed VAT accounting, marketplace deemed-supplier rules, OSS or IOSS may need to be considered.
International transactions should distinguish between the original sale, marketplace or processor balance, conversion charges, exchange gains or losses and the final sterling deposit.
Making Tax Digital for Income Tax has applied since 6 April 2026 to qualifying sole traders and landlords with qualifying income over £50,000. It extends to qualifying income over £30,000 from April 2027 and over £20,000 from April 2028.
Affected taxpayers must maintain digital records, submit quarterly updates using compatible software and complete the required year-end tax-return process.
VAT and international selling rules depend on where the business, customer and inventory are located. Businesses should obtain advice based on their particular supply chain.
When Should You Outsource Ecommerce Bookkeeping?
Managing bookkeeping in-house can become more difficult as an ecommerce business grows. You may want to consider outsourcing your ecommerce bookkeeping when:
- You sell across multiple marketplaces such as Amazon, Shopify, eBay or Etsy.
- You need to manage international VAT registrations and reporting requirements.
- You hold large inventory volumes that require regular tracking and reconciliation.
- Your transaction volume has grown past 100 to 250+ transactions per month, making manual data entry and multi-channel reconciliation time-consuming and prone to errors.
- You receive multi-currency sales and need to manage exchange differences, conversion fees and international payouts.
An ecommerce accountant can help reconcile sales channels and payment processors, maintain accurate records and provide clearer visibility over cash flow and profitability. Working with specialist ecommerce accountants can be particularly valuable as transaction volumes, sales channels and reporting requirements become more complex.
Conclusion
Accurate ecommerce bookkeeping connects every customer order with the corresponding platform report, processor balance and bank deposit. It also separates marketplace fees, refunds, inventory costs, VAT and currency differences so the business can understand its true financial position.
The most important steps are to use an appropriate double-entry system, reconcile every sales channel regularly, monitor inventory and review financial reports each month. As transaction volume and international complexity increase, specialist ecommerce bookkeeping support may provide better control and reduce the risk of reporting errors.
FAQs
What is ecommerce bookkeeping?
Ecommerce bookkeeping is the process of recording and reconciling the financial transactions of an online business. It includes sales, marketplace fees, payment processor charges, refunds, chargebacks, inventory costs, VAT and payouts from platforms such as Shopify, Amazon and eBay.
How is ecommerce bookkeeping different from regular bookkeeping?
Ecommerce bookkeeping involves additional complexities such as multiple sales channels, marketplace settlements, payment processors, inventory accounting, refunds and international transactions. The amount deposited into your bank account may also differ from your gross sales because fees and other deductions are often taken before payout.
How do you reconcile Shopify, Amazon and eBay sales?
Compare sales and settlement reports from each platform with your accounting records and bank deposits. Record gross sales separately from marketplace fees, refunds, commissions and other deductions so that the final payout can be accurately reconciled.
How should Stripe and PayPal payments be reconciled?
Stripe and PayPal reconciliation involves matching transactions and payouts with your accounting records and bank account. Processing fees, refunds, chargebacks, currency conversion charges and other adjustments should be recorded separately rather than treating the net payout as total revenue.
How should refunds and chargebacks be recorded in ecommerce bookkeeping?
Refunds should be recorded against the relevant sales transactions, while chargebacks should be recorded along with any associated processor fees. Keeping them separate helps maintain accurate revenue figures and makes it easier to monitor refund and dispute levels.
Why is inventory accounting important for ecommerce businesses?
Accurate inventory accounting helps ecommerce businesses calculate COGS, gross profit and inventory values correctly. Businesses should keep records of purchases, sales, returns, damaged goods and other stock adjustments to understand the true profitability of their products.
Do UK ecommerce businesses need to register for VAT?
UK ecommerce businesses generally need to register for VAT when their taxable turnover exceeds the applicable VAT registration threshold. VAT obligations can become more complex when selling through marketplaces or internationally, so businesses should regularly review their VAT position and seek professional advice where necessary.
When should an ecommerce business outsource its bookkeeping?
Outsourcing may be worth considering when a business sells through multiple marketplaces, processes a high volume of transactions, manages significant inventory, has international VAT obligations or receives payments in multiple currencies. Specialist support can make reconciliation and financial reporting easier as the business grows.