




A capitalisation table (cap table) is a record of who owns shares in a company and how ownership can shift as the business raises funding or gives equity to employees.
For startups preparing to raise investment, an accurate cap table helps founders understand ownership, model dilution and present investors with a clear picture of the company’s equity structure.
This guide explains what a cap table should contain, how to build one and what UK founders need to know about recording shares, options and convertible investments. Follow along with our Excel template, which includes a funding round model to help you explore potential dilution. Prefer to manage your cap table online? We also introduce dedicated software tools further down the guide.
What Is a Cap Table?
A cap table is a record of who owns what shares in a business. It typically lists shareholders, the number and class of shares owned, and their percentage ownership.
Depending on the stage of the company, it may also track employee share options, convertible investments and other arrangements that could affect future ownership.
Most founders start with a spreadsheet. As the company raises funding and its equity structure becomes more complex, dedicated software or professional advice can help maintain accurate records.
For a more in-depth explanation of ownership and share capital, read our guide: What is Business Equity? Essential Information for Startup Owners and Investors
Why a Cap Table Is Important for Startups
A cap table helps founders to:
- Understand your ownership position before and after issuing shares to investors.
- Evaluate the impact of new share issues and potential equity commitments on current shareholders.
- Record options and other incentives that may affect future ownership.
- Provide consistent ownership information and highlight any outstanding equity commitments.
The cap table should reflect the company’s books and records and relevant agreements. It is not a substitute for the statutory register of members or other statutory records of the company.
Our 12-week investor readiness program can help your startup prepare for fundraising.
What Should Be Included in a Cap Table?
The information needed will depend on the company’s ownership structure and funding arrangements. A cap table will commonly include the following information.
Shareholders and Their Shares
Record each shareholder’s name, the number and class of shares they hold, and their percentage ownership. Keep this information consistent with the relevant share documentation and the company’s statutory records.
Share Classes and Rights
Companies can have different share classes with different voting, dividend, or economic rights. Record the correct class. The rights attached to shares depend upon the company’s articles of association and the terms of those shares.
Read our guides for more guidance on issuing shares and how different share classes affect ownership and shareholder rights: A Founder’s Guide to Issuing Shares When Starting a Company and Understanding Classes of Ordinary Shares and Their Equity Impact
Investment Information
For each round of funding, record relevant information such as amount invested, shares issued, class of shares and resulting ownership. If the transaction affects the company’s equity, update the cap table.
Employee Equity and Other Potential Ownership
Record relevant employee equity arrangements, option pools, warrants and convertible securities. Distinguish these potential future interests from shares that have already been issued.
Advisory shares can affect how a startup allocates equity to its advisers. For more information, see our guide: How Startups Allocate and Manage Advisory Shares.
How to Build a Cap Table for Your Startup
Step 1: Record the Current Owners
Start with the company’s current shareholders. Make a record of the number and class of shares owned by each person and then determine their ownership percentages.
For example, if a founder owns 800,000 of the 1,000,000 shares issued by the company, they have 80% ownership based on issued shares. This percentage may not be equal to 80% of the voting rights or economic entitlement if there are different share classes with different rights.
Example: Ownership Changes with a New Investment
Let’s say Example Ltd has two founders who own 1,000,000 ordinary shares between them, split equally (500,000 shares each). The company then issues 250,000 new shares to an investor. This is a new share issue, rather than a transfer of existing shares from a founder to the investor.
The following example shows how issuing new shares can change the founders’ percentage ownership, assuming all shares carry the same relevant rights and no other equity arrangements apply.
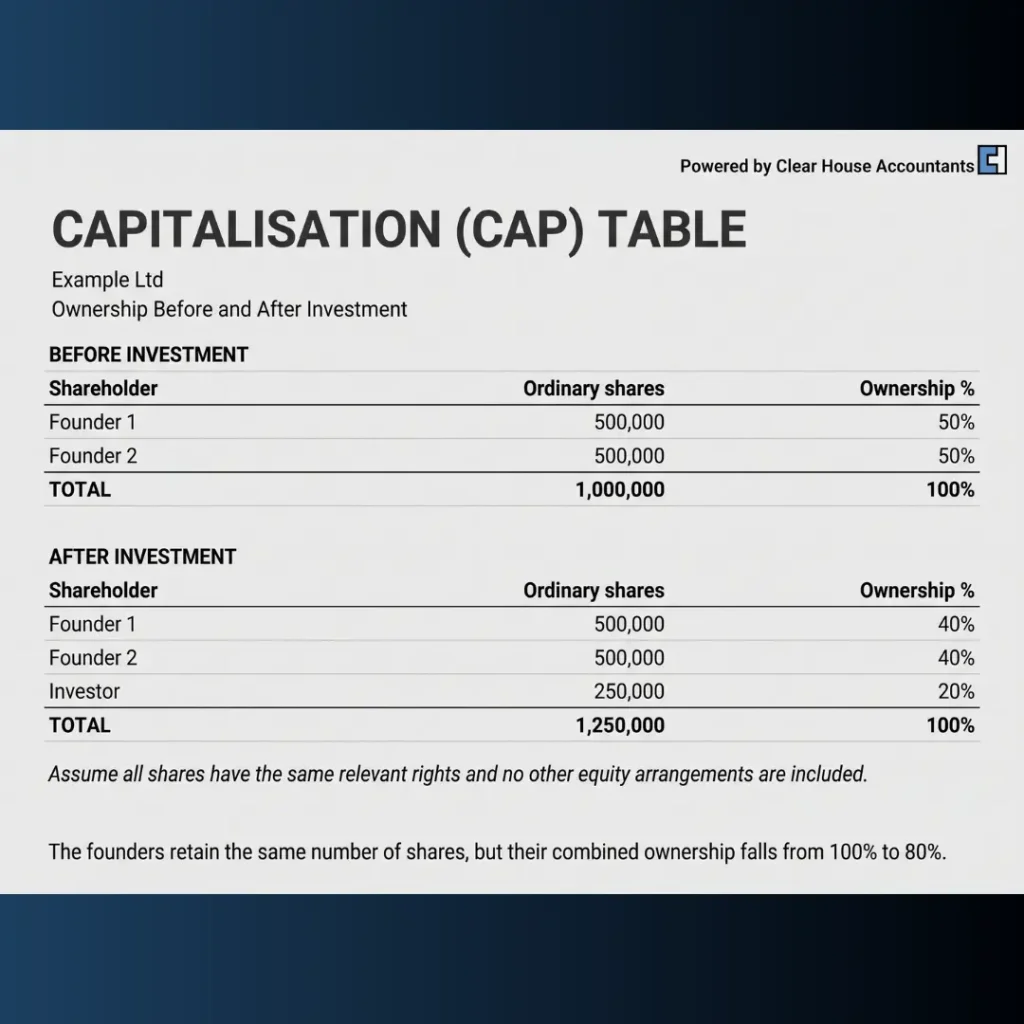
The founders still own the same number of shares, but their combined ownership falls from 100% to 80% because the company has issued new shares to the investor. This illustrates dilution.
This example only shows ownership of issued shares. When you do a fully diluted calculation, you might get a different number if you include options, warrants or other potential equity interests.
Step 2: Record New Investment
When the company issues shares to investors, add the new shareholdings and update the totals and ownership percentages.
Review the impact of the investment on existing shareholders and log the relevant share class and transaction information. It’s not just the amount invested that determines ownership, but also the share price, valuation and terms of the transaction.
Step 3: Add Options and Other Equity Arrangements
Record relevant employee share options, option pools, warrants and convertible securities. Separate issued shares from shares that may be issued in the future.
Track granted options separately from the unallocated pool. If the fully diluted count includes the entire pool, don’t add grants already counted. Specify whether it includes unvested options and the unallocated pool.
For example, 1,000,000 issued shares plus a 100,000-share option reserve equals 1,100,000 fully diluted shares, assuming no other potential equity. A founder with 500,000 shares owns 50% on an issued-share basis and about 45.45% on a fully diluted basis (500,000 ÷ 1,100,000 × 100)
Step 4: Calculate Ownership Consistently
Calculate the percentage for each shareholder with the correct share total.
For ownership of issued shares:
Ownership Percentage = (Number of Shares Held ÷ Total Issued Shares) × 100
If specified potential future shares are included, a fully diluted calculation might yield a different percentage. To make meaningful comparisons, state whether the calculation is based on issued shares or a fully diluted share count.
Step 5: Update the Cap Table After Equity Changes
Update the cap table when shares are issued or transferred, options are granted or exercised, or convertible arrangements convert into shares. Make sure it matches the relevant company records and agreements and review it before fundraising.
When a UK limited company allots shares, it must generally file a return of allotment (form SH01) with Companies House within one month. Check whether the change also affects the company’s people with significant control (PSC) information. The cap table does not replace the company’s statutory records or required filings.
It is also useful to understand how the arrangement affects the company’s share register if shares are held through a nominee. Read our guide to Managing Nominee Shareholders and Legal Transparency in the UK
Equity Arrangements That May Impact a Cap Table
Certain equity arrangements are not shares that have been issued but could impact future ownership and dilution. Their treatment is subject to the terms of the relevant agreement.
Employee Option Pools and Share Options
Share options give eligible employees the right, but not the obligation, to acquire shares under specified terms and conditions. An option pool is a portion of a company’s equity reserved for potential future share option grants.
When modelling dilution, account for the option pool and track grants, vesting and exercises.
From 6 April 2026, EMI limits increased for most eligible companies. The changes include higher company option-value, gross-asset and employee limits, as well as an extended qualifying exercise period for eligible options. Check the current HMRC eligibility and reporting requirements before implementing an EMI scheme.
Convertible Investments (Loan Notes, ASAs and SAFE Agreements)
Convertible investments like convertible loan notes, Advance Subscription Agreements (ASAs) and Simple Agreements for Future Equity (SAFEs) delay valuation and equity allocation until a future round. Record the relevant agreement and terms that may affect the number or class of shares issued.
These arrangements carry distinct tax treatments. For example, HMRC mandates strict conditions (such as long-stop dates and non-refundable investment status) for an ASA to qualify for SEIS or EIS tax relief.
Warrants and Other Equity Awards
Holders of warrants and other equity awards may be entitled to acquire shares in the future. Record all relevant outstanding commitments and explain the treatment of such commitments in the calculation of fully diluted ownership.
Common Cap Table Mistakes to Avoid
Common issues include:
- Outdated information or not recording changes after a share issue, transfer or option grant.
- Excluding or not considering convertible investments or other deals that could result in shares in the future.
- Inconsistent calculation or combining issued-share ownership with fully diluted ownership without explaining the difference.
- Conflicting records of the ownership records that are inconsistent with the company’s official records or transaction documents.
A current cap table will make ownership easier to review, but should be checked against the company’s statutory records and relevant agreements, not treated as the sole legal record of ownership.
Tools for Cap Table Management
As the company brings in investors and introduces different share classes, employee options or convertible investments, equity management software can make updates and scenario modelling easier.
Examples of cap table management tools include Carta, Ledgy and Cake. Check their current features, availability and pricing to determine whether they meet your company’s needs. Software does not replace accurate transaction records or legal and tax advice.
Do UK Startups Need a Cap Table?
A cap table is a useful tool for managing ownership, especially when a startup is getting ready to raise investment or issue equity. It is not a substitute for statutory company records in itself.
UK companies are required to maintain a register of members, which records their legal members. A cap table is a separate management tool used to analyse share ownership and model potential dilution. The cap table should be checked against the register and relevant share documentation. Where shares are held through a nominee, legal ownership and beneficial interests may need to be considered separately.
Conclusion
A cap table tells startup founders who owns the company and how ownership could change with funding, employee share options and other arrangements.
Keep good records of the shares issued. Show issued-share ownership separately from the fully diluted ownership. Update the table when equity changes. Make sure that it is consistent with the company’s records and relevant agreements before fundraising.
If your startup is preparing for investment, our Startup Accountants can help with cap table setup, dilution planning and investor readiness.
FAQs
How Frequently Should a Startup Update Its Cap Table?
Update whenever a transaction results in a change in share ownership or a creation, change or settlement of a relevant equity commitment. Review it before fundraising and compare it with the company’s records.
Does Dilution Appear on a Cap Table?
Yes. A cap table can be used to show current ownership and to model the effect of new share issuances or potential future shares on existing shareholders. The calculation should state if it is based on issued shares or on a fully diluted basis.
What is the difference between a cap table and a register of members?
A cap table is an internal strategic tool for analysing share ownership and potential dilution, while the register of members records the company’s legal members. A cap table does not replace the register or other required statutory records.
When should a startup create its first cap table?
A startup should create a cap table as soon as shares are issued to founders or other shareholders to keep ownership records accurate.