




ISAs, or Individual Savings Accounts, have become a go-to choice for many people in the UK looking to save or invest their money smartly. The tax advantages that come with these accounts make them quite popular.
ISAs come in various forms, including Junior ISAs, Innovative Finance ISAs, Cash ISAs, Stocks and Shares ISAs, and Lifetime ISAs. These Individual Savings Accounts (ISAs) cater to long-term or short-term savings, portfolio building, retirement planning, and providing cash for your child’s future.
This comprehensive guide will examine the specifics of each ISA, including its characteristics, eligibility conditions, and special benefits.
What Are ISAs?
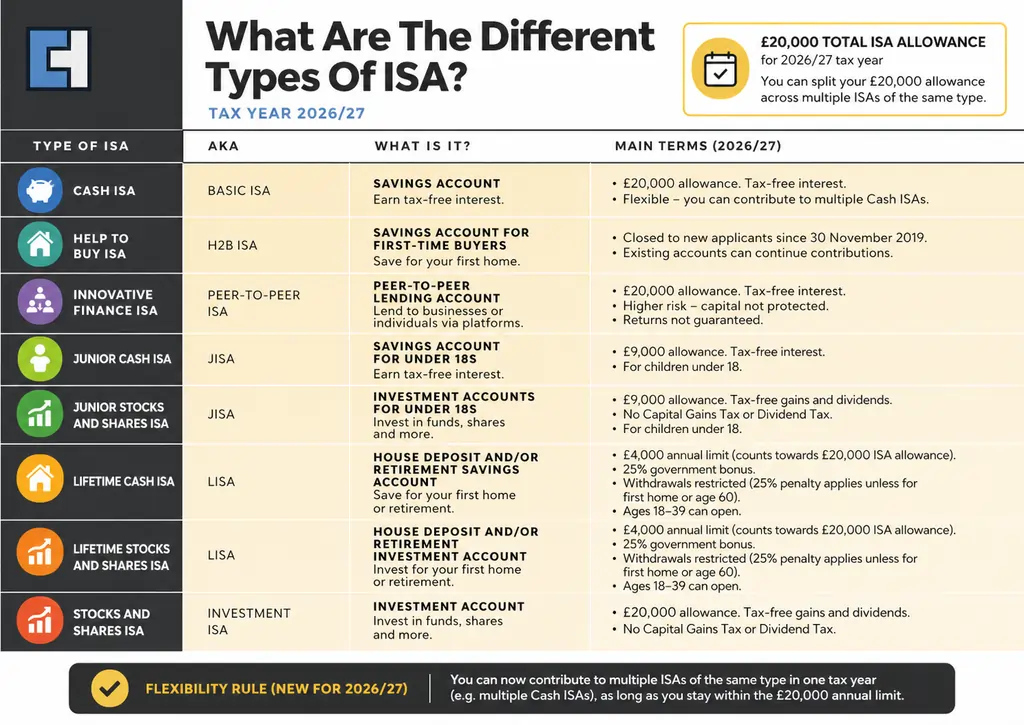
An Individual Savings Account (ISA) is a tax-efficient savings or investment account that allows eligible interest, dividends and investment gains to grow tax-free. There are different types of ISA to suit different savings and investment needs, each with its own eligibility and contribution rules.
- For the 2026/27 tax year, the overall ISA allowance is £20,000. This allowance can be used across different ISA types, including Cash ISAs, Stocks and Shares ISAs, Lifetime ISAs, and other eligible accounts.
- Your yearly allowance is reset each time a new tax year begins.
- You can transfer your existing Individual Savings Accounts (ISAs) to your new ISA.
- Children under 18 can hold a Junior ISA. To open and pay into an adult Cash ISA or Stocks and Shares ISA, an individual must be aged 18 or over.
- Customised options are available to help individuals save for their first home purchase or retirement.
- For flexible ISAs, you can replace withdrawals without affecting your allowance within the same tax year.
The Different Types of ISA Accounts
The main 5 individual Savings Account (ISA) options are available to adults and kids.
- Cash ISAs
- Stocks and shares ISAs
- Lifetime ISA
- Innovative Finance ISA
- Junior ISAs
Junior ISAs are tax-free savings accounts for children under 18 and can be opened by a parent or guardian.
Cash ISAs
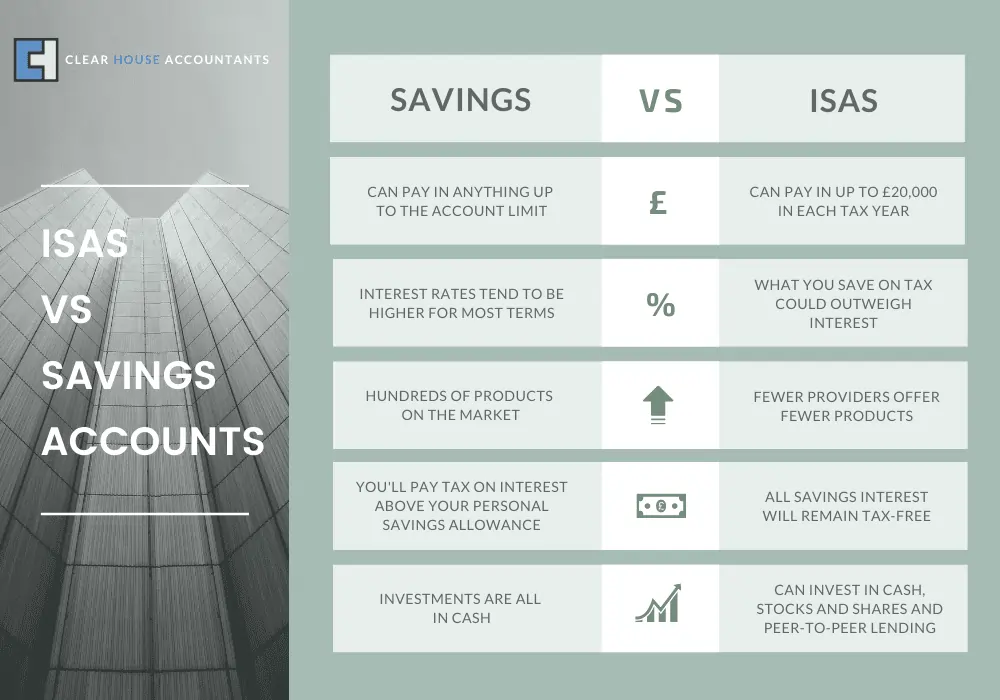
Cash ISAs are very similar to regular savings accounts, and your savings interest isn’t taxed when it comes to Cash ISAs. You’ve got quite a few cash ISAs to pick from, too. They might seem like they all function the same way, but actually vary in terms of profit, access terms and conditions.
The Autumn Budget 2026 confirmed that the planned reduction of the Cash ISA limit to £12,000 for individuals under 65 will not go ahead.
Easy Access ISAs
Easy access ISAs represent the most straightforward kind of cash ISA. They are specially designed to give you free access to your money whenever you desire. Typically, these ISAs permit an unlimited number of deposits and withdrawals with no penalties, although it’s essential to remember that some may have certain restrictions.
In most cases, easy access ISAs come with fluctuating interest rates. It means your initial rate can increase or decrease over time.
Fixed-rate ISA
This type of cash ISA is where your initial deposit is stashed away for a set period and earns a fixed rate of interest during that time. This period could be anything from one to five years, with longer terms usually offering higher interest rates.
Note: If you try to withdraw from your fixed rate ISA before the period ends, you could pay an interest penalty, and your ISA might even be closed after a warning.
Notice ISA
This option can provide you with higher interest rates than a standard, easy-access ISA, and it offers you more flexibility to withdraw money than a fixed rate ISA might allow. However, to withdraw money, you’ll need to notify the bank in advance, with notice periods generally ranging from 30 to 180 days. If you withdraw without adequate notice, you’ll face a penalty, the scale of which often matches the notice period.
Regular Savings ISA
A regular savings ISA might be your best bet if you want to save smaller amounts regularly. This type of ISA offers a better interest rate, provided you commit to making traditional, minimum deposits. However, if you withdraw prematurely, you might face a penalty.
Stocks and Shares ISAs
A stocks and shares ISA, also known as an investment ISA, invests your deposited money into funds, bonds, and shares. Even though stocks and share ISA can potentially boost your savings as the stock market grows, it’s crucial to remember that risk is involved. Your investment might lose value.
The Financial Services Compensation Scheme (FSCS) provides protection of up to £85,000 per eligible person, per authorised firm for qualifying investment claims if an investment provider fails. Cash ISA deposits held with eligible UK-authorised banks, building societies or credit unions are protected up to £120,000 per eligible person, per authorised firm from 1 December 2025. FSCS protection does not cover losses caused by investment performance or changes in market value.
Lifetime ISA
The Lifetime ISA (LISA) is designed to help eligible individuals save towards their first home or retirement, with a government bonus on qualifying contributions.
However, there are specific criteria and limitations associated with opening a LISA. Eligibility requires:
- You should be between 18 and 40, with the first deposit made before reaching 40.
- You can make contributions up to £4,000 per year until age 50.
- After turning 50, the Government bonus ceases, but the savings continue to earn interest.
- Withdrawals from a LISA are permitted for purchasing a qualifying first home, reaching the age of 60 or above, or being terminally ill with less than a year to live.
- For a charge-free first-home withdrawal, the property must cost £450,000 or less. From 29th October 2026, If the property costs more than £450,000, a 20% withdrawal charge applies to an otherwise qualifying purchase. Other unauthorised withdrawals can incur a 25% withdrawal charge.
First Time Buyer ISA (from April 2029)
The government will introduce a new First Time Buyer ISA from April 2029, replacing the Lifetime ISA for new savers. It will offer a 25% government bonus on the final account balance when withdrawn to buy a first home worth up to £450,000. Contributions will be limited to £4,000 per year, with the total government bonus capped at £20,000. Existing Lifetime ISA holders will be able to continue using and contributing to their accounts under the current rules.
If you opt for a Lifetime ISA (LISA) as a retirement savings vehicle, you can withdraw funds from your account at age 60. Utilising the savings for your needs is permissible, although the LISA is primarily intended to provide financial support in retirement.
Innovative Finance ISA
In the realm of peer-to-peer lending (P2P), an Innovative Finance ISA (IFISA) allows individuals to lend their deposited funds to individuals or small businesses, or to invest in crowdfunding projects, for a predetermined period.
The aim is to generate tax-free returns on the initial investment after the specified timeframe. It’s important to note, however, that returns are not guaranteed, and there is a level of risk involved with the invested capital. Peer-to-peer investments held in an IFISA are not protected by the FSCS against investment losses, such as borrower defaults.
How Do You Transfer an ISA?
You can move your ISA savings to a different provider, including another type of ISA, whenever you wish, depending on the provider’s terms.
If you have money saved from previous tax years, it will not affect your allowance. Any money, no matter how big or small, can be transferred at your discretion. For example, you may transfer £15,000 from an existing Cash ISA to a Stocks and Shares ISA using the official ISA transfer process. Transfers of previous ISA savings do not normally count towards your annual ISA allowance, allowing you to continue using your available allowance for new contributions.
You can transfer some or all of your current-year ISA subscriptions, including investments bought with those subscriptions and any income arising from them. Partial transfers of current-year subscriptions are permitted, subject to the receiving provider’s terms. After the transfer is finished, you will still have some permissions. There are a few important things to remember when moving your ISA. First off, taking physical withdrawals of the funds is not recommended, as it may result in losing tax-free status; instead, use the official ISA transfer process.
When you switch to a new provider, you may be required to pay an additional fee for the initial set-up or advice. Transferring a Lifetime ISA to another type of ISA before the age of 60 is treated as a withdrawal and normally attracts a 25% withdrawal charge, unless an exemption applies, such as where the investor is terminally ill.
How Do You Open an ISA? | Setting up an ISA
Different banks give you several ways to operate an Individual Savings Account (ISA). You can easily open an ISA in the UK if you’re a UK resident or Crown servant abroad. You can go to a local branch, send an application by mail, use their online platform or a mobile app, or even call them.
Usually, you’ll need to deposit an initial amount to open an ISA, which can vary from as little as £1 to thousands of pounds. However, some ISAs might require you to commit to a minimum regular deposit each month.
The provider of the ISA will also require certain personal information from you, such as your complete name, address, national insurance number, and signature. You must thoroughly read the ISA provider’s declaration and carefully comprehend any limitations or fees associated with withdrawing funds from your ISA.
How many ISAs can you have?
Since 6 April 2024, adults can pay into multiple Cash ISAs, Stocks and Shares ISAs and Innovative Finance ISAs of the same type in one tax year, subject to the overall annual ISA allowance and provider terms. However, you can pay into only one Lifetime ISA in each tax year.
A child can hold one Cash Junior ISA and one Stocks and Shares Junior ISA. Contributions can be made to both, but the combined annual contribution limit is £9,000 for the 2026/27 tax year.
Can you withdraw from an ISA and deposit the funds later?
With a ‘flexible’ ISA, you can withdraw and replace funds within the same tax year without using up your allowance. This includes deposits from previous years; repaying them before the tax year ends doesn’t affect your current annual limit. However, withdrawals of funds from previous tax years must be replaced into the same flexible ISA from which they were withdrawn, within the same tax year.
By contrast, reinvesting money taken from a non-flexible ISA counts as a new contribution toward your allowance. Transferring funds to a standard account ends their tax-exempt status, making them subject to HMRC tax rules and your personal savings allowance.
Conclusion
In summary, Individual Savings Accounts (ISAs) provide valuable tax advantages by allowing eligible savings interest, dividends, and investment gains to grow within a tax-efficient account.
When deciding what to buy, it’s critical to understand the subtle differences between the types of ISAs. Your goals and financial status should guide the decisions you make. When selecting the best individual savings account (ISA) for you, don’t forget to consider your risk tolerance, investment horizon, and specific savings objectives.