




In this UK Personal Tax guide by Clear House, you’ll explore Income Tax, NICs, Capital Gains Tax, dividends, pensions, Inheritance Tax, savings interest, student loans, HICBC, and personal tax allowances. The guide also covers tax rates, allowances, and filing rules.
Before we discuss each tax in detail, let’s start with the basics of personal taxes!
What are UK Personal Taxes?
UK Personal taxes are levied directly or indirectly on individuals (not companies) on their personal income, gains, assets, and spending. These are further divided into categories.
- Direct personal taxes: paid directly by you, like Income Tax, National Insurance, Capital Gains Tax, Dividend Tax, IHT, etc.
- Indirect personal taxes: These are added to the price of goods/services and collected by businesses, such as VAT, fuel duty, and excise duties.
Where Do You Fit?
If you’re not sure where to get started, you can jump straight to taxes that matter most to you. You can just click on the taxes you are interested in.
Employees: If you are an employee, you might focus on Income Tax and National Insurance (NI). It covers how you are taxed and how much salary is deducted through PAYE.
Self-Employed (Freelancers): If you are self-employed or a freelancer, you can explore Income Tax, NICs, and Self-Assessment to report and pay your taxes.
Landlords: If you are a landlord with rental income, you can check how Income Tax (tax on rental income) and Capital Gains Tax work.
Company Directors: Directors can explore the details of Dividend Tax and Income Tax to learn how they are taxed .
Investors: Investors who invest in shares or assets can visit the Capital Gains Tax, Dividend tax, Foreign Income Tax, Chargeable Event Gains, and Saving Interest Tax, along with the Personal Saving Allowance, to minimise their taxes.
Beneficiaries: Estate beneficiaries can get detailed information on thresholds, exemptions and reliefs related to Inheritance Tax (IHT).
Pension Holders and Retired Personnel: They can explore Income Tax, Pension Tax, and Retirement Tax to learn about the tax implications and available relief.
High Earners: Our guide covers the High Income Child Benefit Charge (HICBC), Capital Gains Tax, Foreign Income Tax, Chargeable Event Gains, Income Tax, and Self Assessment Reporting requirements.
No matter which category you fall into, understanding personal taxes helps you make informed decisions for a safe and secure future. Read on to explore how learning personal taxes protects you.
Why Personal Taxes Matter
Complying with Personal tax helps you save money, avoid costly mistakes, and reduce stress. Getting it wrong can be financially and emotionally costly. It impacts major financial decisions.
Income Tax and NICs reduce your take-home pay. You may pay Capital Gains Tax when disposing of shares or selling a buy-to-let property, and Dividend Tax on taxable dividend income. Stamp Duty Land Tax is applied when buying a house. Most pension income is subject to Income Tax when received, although eligible tax-free pension lump sums may be available.
Non-compliance, like missing a Self-Assessment deadline, can lead to penalties, interest, and even HMRC enquiries. However, good personal tax planning can save you from punishments and reward your time and attention.
Income Tax – The Core Personal Tax
Income Tax is the main personal tax in the UK, charged on most types of income. For employees, it is usually deducted from salary through PAYE. You pay Income Tax on profits from your business, interest from your savings and investments, and rental income from buy-to-let property. Dividend income is taxed separately using the applicable dividend tax rates.
Income Tax is charged on taxable income above your Personal Allowance, at rates that depend on the type of income and where in the UK you live. From 6 April 2027, property income tax rates are set to be 24% for basic-rate taxpayers, 44% for higher-rate taxpayers and 49% for additional-rate taxpayers. These announced rates apply in England, Wales and Northern Ireland, while the Scottish and Welsh governments have powers to set property income rates in line with their existing Income Tax powers.
National Insurance Contributions (NICs)
National Insurance is a tax applied to earnings and self-employed profits. The age and earnings thresholds for National Insurance contributions depend on the type of contribution and your employment or self-employment circumstances. Class 1 National Insurance is deducted through PAYE from employees’ earnings, and employers also pay contributions.
Compulsory Class 2 National Insurance contributions were abolished from 6 April 2024, although voluntary contributions remain available. For 2026/27, Class 4 contributions are payable at 6% on profits between £12,570 and £50,270 and 2% on profits above £50,270.
Learn more about Income Tax and National Insurance in these guides.
Making Tax Digital for Income Tax
Making Tax Digital for Income Tax applies in stages to sole traders and landlords with qualifying gross income above the following thresholds:
- More than £50,000 in the 2024/25 tax year: applies from 6 April 2026.
- More than £30,000 in the 2025/26 tax year: applies from 6 April 2027.
- More than £20,000 in the 2026/27 tax year: applies from 6 April 2028.
Those affected must use compatible software to maintain digital records and submit quarterly updates to HMRC. The thresholds are based on qualifying gross income before expenses.
Capital Gains Tax (CGT)
Capital Gains Tax (CGT) is the tax on profit or gain by selling, giving, exchanging, or disposing of an asset. For 2026/27, the annual exempt amount is £3,000 for individuals. You only pay CGT if your overall gains, after deducting allowable losses and applying relevant reliefs, exceed this amount. CGT rates depend on your income tax band and the type of asset.
If you’re new to Capital Gains Tax, looking for changes to CGT when selling property, or want to minimise your CGT, read these guides.
Now that you know the tax on property or asset gain, let’s explore whether you are exempt from paying tax on interest earned through savings.
Savings Interest Tax
Interest earned from savings is taxable, but you may be able to receive some interest tax-free using your available allowances. Your Personal Allowance may cover savings interest if it has not already been used against other income. You may also qualify for the Starting Rate for Savings (up to £5,000 if your other taxable income, excluding savings interest and dividends, is below £17,570) and the Personal Savings Allowance (£1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and £0 for additional-rate taxpayers).
Savings interest may arise from bank and building society accounts, peer-to-peer lending, unit trusts, government bonds and gilts. Tax is paid at your normal income tax rate (20%, 40%, or 45%) on interest beyond tax-free savings for 2026/27. From 6 April 2027, these savings income tax rates will increase to 24% for basic-rate taxpayers, 44% for higher-rate taxpayers and 49% for additional-rate taxpayers.
Tax is usually collected through tax code adjustments or PAYE. If you have untaxed income or large amounts, you may need to report it through Self Assessment. Interest from certain National Savings accounts and ISAs is tax-free and exempt from your savings allowance. For 2026/27, you can subscribe up to £20,000 across eligible adult ISAs, including Cash, Stocks & Shares and Lifetime ISAs. The planned reduction in the Cash ISA limit was cancelled in the Autumn Budget 2026.
If you have invested in a company as a shareholder, you will pay dividend tax on your income earned from shares. Read on to learn more.
Dividend Tax
Dividends Tax is levied on the income you receive from owning shares in a company. Some of the dividend income is tax-free each year. The current dividend allowance is £500. The tax you pay on dividends above this allowance depends on your income tax band: 10.75% for basic rate taxpayers, 35.75% for higher rate taxpayers, and 39.35% for additional rate taxpayers for the 2026/27 tax year.
You may need to report dividends through Self Assessment if they exceed your allowances or are not fully taxed at source.
Learn how dividend tax works in this detailed guide.
Inheritance tax can be overwhelming when you don’t know what it is. Let’s find it.
Inheritance Tax (IHT)
Inheritance Tax is applied to the estate (money, property, or possessions) of a deceased person. The standard Inheritance Tax nil-rate band is £325,000. An additional residence nil-rate band of up to £175,000 may apply when a qualifying home is passed to direct descendants. This additional band is reduced by £1 for every £2 that the estate exceeds £2 million. Inheritance Tax is generally charged at 40% on the taxable estate above the available thresholds, after applicable exemptions and reliefs.
From 6 April 2027, most unused pension funds and pension death benefits will be included in the deceased person’s estate for Inheritance Tax purposes. From 6 April 2026, a combined £2.5 million allowance applies to qualifying agricultural and business property eligible for 100% Agricultural Property Relief or Business Property Relief, with 50% relief generally applying to qualifying value above that allowance.
If you are looking for ways to reduce your Inheritance tax? Don’t miss this post.
If you are planning for retirement, you must not miss out on the retirement tax.
Pensions & Retirement Taxation
Most pension income is subject to Income Tax when received, although eligible tax-free pension lump sums may be available.
For the 2027/28, 2028/29 and 2029/30 tax years, individuals who are above State Pension age or reach State Pension age during the relevant tax year may qualify for a Pension Tax Allowance that reduces their Income Tax liability. The full reduction is available where total income does not exceed the full new State Pension. Above that level, the reduction is tapered by £1 for every £3 of additional income.
You can usually take up to 25% of your pension as a tax-free lump sum, subject to the standard Lump Sum Allowance of £268,275. The normal minimum pension age is currently 55 and will rise to 57 from 6 April 2028 for most people, although some individuals have a protected pension age.
Income Tax is usually deducted from pension payments by your provider, and you may need to submit a Self Assessment tax return depending on your income sources and level.
Pension income can add to your total income. This may push you into higher tax bands, reduce allowances, or trigger other charges. Planning and getting advice from a personal tax accountant can help you save tax.
If you want to maximise your retirement savings, don’t miss these guides.
In addition to these personal taxes, there are other miscellaneous taxes you need to be aware of.
Other Personal Taxes in the UK
These are some of the other Personal Taxes in the UK:
Student Loan Repayments
You repay these loans when your income exceeds a certain threshold. Repayments are usually made at the same time as tax or National Insurance when you are an employee. Repayments are usually made through PAYE or Self Assessment and are based on your income above the relevant repayment threshold.
High Income Child Benefit Charge
If you or your partner receives Child Benefit and either of you has adjusted net income above £60,000, the person with the higher adjusted net income may have to pay the High Income Child Benefit Charge. The charge is 1% of the Child Benefit received for every £200 of adjusted net income above £60,000. It reaches 100% when adjusted net income is £80,000 or more.
Crypto & Foreign Income
Individuals may have to pay Capital Gains Tax when they dispose of crypto-assets. For 2026/27, the applicable CGT rates are generally 18% or 24%, depending on their taxable income. UK residents are generally subject to UK tax on their worldwide income, subject to applicable exemptions and reliefs. Non-UK residents may also have UK tax obligations on certain UK-source income and gains.
Since 6 April 2025, qualifying new UK residents who have been non-UK resident for at least 10 consecutive tax years may claim relief on eligible foreign income and gains arising during their first four years of UK residence under the Foreign Income and Gains (FIG) regime.
If you’re new to cryptocurrency, this post will show you how to start investing and why it’s worthwhile.
Chargeable Event Gains
Chargeable event gains are taxed as income. These may relate to a life insurance policy, capital redemption policy, or life annuity contract. Chargeable event gains on bonds are treated as savings income and taxed at the applicable savings income tax rates explained in the Savings Interest Tax section.
If you qualify for the starting rate for savings, up to £5,000 of income may be taxed at 0%, depending on your other income. Your non-savings income must be within certain limits after your Personal Allowance. You may also benefit from the Personal Savings Allowance (£1,000 for basic-rate, £500 for higher-rate, £0 for additional-rate taxpayers), which can reduce the tax payable on these gains.
Chargeable event gains are reported on Self Assessment. You may be able to claim top-slicing relief to reduce the tax payable.
Personal Tax Allowances & Reliefs
These are some of the major personal tax allowances and reliefs:
Personal Tax Allowance
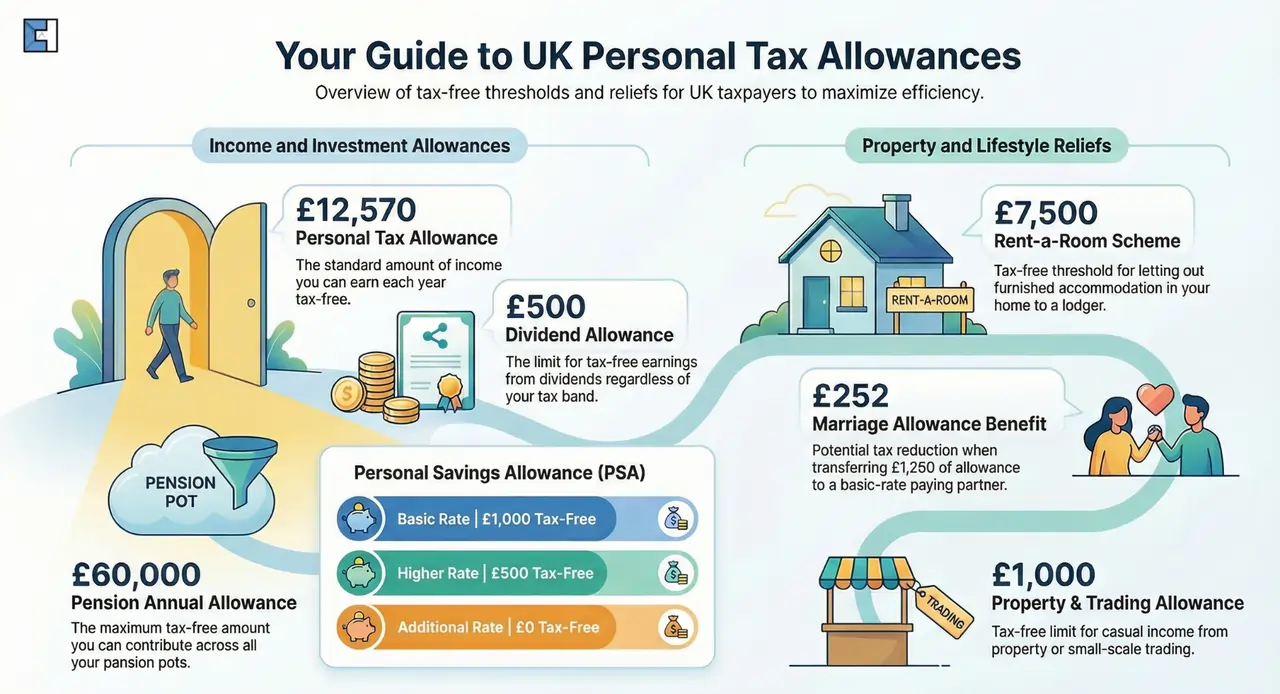
The Personal Allowance is the amount of income you can receive before paying Income Tax. It is £12,570 for 2026/27 and is frozen at this level until 5 April 2031. It is reduced by £1 for every £2 of adjusted net income above £100,000.
Personal Savings Allowance
With Personal Saving Allowance (PSA), you can earn interest on your savings tax-free. This allowance is applied based on your Income Tax band. Basic-rate taxpayers can earn £1,000 in savings interest; higher-rate taxpayers can earn £500; and additional-rate taxpayers do not get an allowance.
Dividend Allowance
Dividend allowance is the amount you earn from dividends without paying any tax on them. Currently, the allowance is £500. How much you pay on dividends over your dividend allowance depends on your Income Tax band.
Marriage Allowance
This allowance allows you to transfer £1,260 of your Personal Allowance to your spouse or civil partner. It brings down your tax by up to £252 in the tax year. To avail this allowance, you must be married or in a civil partnership, you don’t pay income tax, and your partner pays income tax at a basic rate.
Married couples and civil partners can save tax through valuable allowances and reliefs. Read this guide.
Blind Person’s Allowance
This allowance is an extra amount added to the annual Personal Allowance of blind or severely sight-impaired individuals. In 2026/27, the Blind Person’s Allowance is £3,250.
Property or Trading Allowance
The property allowance and trading allowance are separate allowances, each currently set at £1,000. The property allowance applies to qualifying property income, while the trading allowance applies to qualifying trading or miscellaneous income. From 6 April 2027, the trading allowance will increase to £3,000, while the property allowance will remain at £1,000.
Rent-a-Room Scheme
The Rent a Room Scheme allows resident landlords to earn up to £7,500 a year tax-free from letting furnished accommodation in their only or main home. The limit is reduced to £3,750 if the rental income is shared with someone else.
Pension Annual Allowance
Many people get relief from pension savings. The Pension Annual Allowance is the maximum amount of pension savings that can be built up across your pension schemes in a tax year before an Annual Allowance tax charge may apply. It is £60,000 for 2026/27. Employer contributions count towards this limit, and the allowance may be lower for high earners or people who have flexibly accessed their pension.
Other tax reliefs and allowances include Gift Aid relief.
Personal Tax Filing & Deadlines
Wondering when to file your personal tax? You’ll normally need to register for a Self Assessment tax return by 5 October following the end of the tax year in which you became eligible. For paper tax returns, the deadline is 31st October. The online tax return deadline is 31st Jan. To pay any due tax (including the first payment on account), the deadline is 31 January. The last date of the second payment on account (if applicable) is 31 July.
Conclusion
This comprehensive guide explains all major UK personal taxes. It will help employees, self-employed, landlords, investors, or pensioners protect their finances and avoid costly mistakes. If you are struggling with your personal tax compliance, a qualified personal tax accountant ensures accurate Self-Assessment, maximises allowances, minimises liabilities, protects you from penalties and handles your finances effectively.