




A company car has always been considered the epitome of benefits provided by an employer to their employees. Still, with people getting more aware of the alternatives to company cars, a question has arisen on everyone’s mind. Company car or Car Allowance, which one is better?
This guide will look at both sides of the debate to help you decide which one would be better.
What Is A Company Car?
Limited Companies often tend to provide incentives to their employees and benefits on top of their remuneration. One such incentive is to provide an employee with a mode of commuting in the form of a company vehicle.
A company car is a vehicle offered to employees by employers for personal or business use to provide them with commuting benefits. This offer is usually made to individuals whose job description requires them to travel around often for business purposes.
If employees are provided with a vehicle to commute, in that case, the total amount, equivalent to the total market value of the car, is added to the employee’s annual remuneration package. This approach is usually adapted to levy some of the taxes as the subsequent deductions are made by the employee receiving the benefits.
A company car is an exceptional way of relieving some financial stress away from employees while keeping their loyalties directed towards the business. However, if employees are provided with such an incentive, they need to be aware of the tax obligations that come with it.
Tax Liabilities On Company Car
The tax liability incorporated with a company car is also known as the Benefit In Kind. BiK tax and is a little complicated to work with; however, we have made it as simple to understand as possible.
The benefit-in-kind (BiK) tax might get a little confusing, as there are several variables involved in calculating BiK for a company car, such as the different tax rates applied to carbon-emission cars compared to electric vehicles. Additionally, diesel cars that do not meet the relevant RDE2 emissions standard may be subject to a 4 percentage-point supplement to the BiK rate. The overall appropriate percentage cannot exceed 37%.
The taxable company-car benefit is calculated using the car’s P11D value and its applicable BiK percentage. The resulting taxable benefit is then used to calculate the employee’s Income Tax liability.
The following factors are what affect the rate of company car tax that employees receiving the benefits are liable to pay.
- The age of the car.
- The engine size.
- The CO2 emission of your car.
- The fuel used by your company car.
- The P11D value of your car.
- Your income tax band.
Employees also get tax relief if they are provided with plug-in hybrids or electric cars.
Calculating The Benefit In Kind (BiK) Tax Applicable
The following formula can be applied to calculate the BiK tax,
P11D value in pounds x percentage BiK rates x Income Tax Band percentage = Annual BiK tax payable
For example, suppose an employee has a company car with a P11D value of £25,000 and is a basic-rate taxpayer. If the car’s CO₂ emissions are between 105 and 109 g/km, the applicable BiK rate for the 2026/27 tax year is 27%.
The annual taxable benefit would be:
£25,000 × 27% = £6,750
For a basic-rate taxpayer paying Income Tax at 20%, the annual company-car benefit tax would be:
£6,750 × 20% = £1,350
This is an illustrative calculation. The actual amount depends on the employee’s tax position and the period for which the car is available.
Company Car BiK Rates for 2026/27
The Benefit-in-Kind (BiK) percentage for a company car depends on its CO₂ emissions and, for qualifying plug-in hybrid vehicles, its electric driving range. The following rates apply for the 2026/27 tax year.
CO₂ emissions (g/km) | Electric range (miles) | NEDC BiK rate (%) | WLTP BiK rate (%) |
0 | N/A | 4 | 4 |
1–50 | 130 and above | 4 | 4 |
1–50 | 70–129 | 7 | 7 |
1–50 | 40–69 | 10 | 10 |
1–50 | 30–39 | 14 | 14 |
1–50 | Less than 30 | 16 | 16 |
51–54 | N/A | 17 | 17 |
55–59 | N/A | 18 | 18 |
60–64 | N/A | 19 | 19 |
65–69 | N/A | 20 | 20 |
70–74 | N/A | 21 | 21 |
75–79 | N/A | 21 | 21 |
80–84 | N/A | 22 | 22 |
85–89 | N/A | 23 | 23 |
90–94 | N/A | 24 | 24 |
95–99 | N/A | 25 | 25 |
100–104 | N/A | 26 | 26 |
105–109 | N/A | 27 | 27 |
110–114 | N/A | 28 | 28 |
115–119 | N/A | 29 | 29 |
120–124 | N/A | 30 | 30 |
125–129 | N/A | 31 | 31 |
130–134 | N/A | 32 | 32 |
135–139 | N/A | 33 | 33 |
140–144 | N/A | 34 | 34 |
145–149 | N/A | 35 | 35 |
150–154 | N/A | 36 | 36 |
155–159 | N/A | 37 | 37 |
160–164 | N/A | 37 | 37 |
165–169 | N/A | 37 | 37 |
170 and above | N/A | 37 | 37 |
The maximum appropriate percentage for company-car benefits is 37%, including any applicable diesel supplement.
How To Work Out Company Car Tax?
The following factors are what determine the value of company car tax, or the P11D value:
- CO2 Emissions
- The Fuel Type of the Car
- The Value of the Car
- Personal Tax Rate
- Personal Contributions
Carbon Dioxide Emissions:
A company car’s Benefit-in-Kind (BiK) percentage depends on its CO₂ emissions, fuel type and, for qualifying plug-in hybrids, electric driving range. For the 2026/27 tax year, the applicable percentage ranges from 4% for zero-emission cars to a maximum of 37% for higher-emission vehicles.
Use HMRC’s 2026/27 company-car BiK table to identify the correct percentage for the vehicle. Diesel cars that do not meet the relevant RDE2 emissions standard may be subject to a 4 percentage-point supplement, but the overall BiK percentage cannot exceed 37%.
What Is My P11D Value?
The P11D is a form that an employer needs to fill out for each employee, current or former, upon request, at the end of every fiscal year if they provide their employees with any benefit. This form is put in place to protect the benefit of the state and restrict businesses from abusing the benefit-in-kind system for personal gains.
P11D values are the monetary values assigned to the car in the P11D form, as it is difficult to charge tax on a second-hand vehicle or a vehicle in use. Hence, HMRC uses listing prices and P11D values to evaluate the car and generate a tax amount.
The P11D values are calculated by summing up,
- The listing price of the vehicle.
- Cost of delivery.
- VAT
- Optional extra fees
Do note that HMRC does not include road tax and the first year’s registration fee in the P11D calculation.
Reporting Company Cars to HMRC: Requirements for Employers
If you provide company cars for directors or employees, it’s essential to inform HM Revenue and Customs (HMRC) to avoid compliance issues. This applies when a car is made available for private use, including home-to-work journeys (unless the work location is temporary). Below is a summary of the process and requirements for reporting, along with key deadlines.
What to Report
You must notify HMRC by submitting a P46 (Car) form when you:
- Provide a company car to an employee for the first time.
- Stop providing a company car to an employee.
- Add a second or additional car for an employee’s use.
Ways to Submit the P46 (Car) Form:
- Online submission: Fill out the form and send a printed copy to the address provided.
- PAYE Online service: Use HMRC’s PAYE Online portal, specifically designed for employers.
- Payroll software: Many payroll software packages offer direct submission options.
Additionally, report any car benefits annually on your end-of-year forms, paying Class 1A National Insurance on the car’s benefit value.
Replacing a Company Car
If a company car is replaced, you also need to update HMRC. Use any of the following methods:
- HMRC’s PAYE Online service.
- Payroll software.
- Your annual end-of-year forms.
Important Deadlines
The deadline to report company car changes depends on the timing of the change:
| Change Date Range | Electronic Submission Deadline | Printed Submission Deadline |
|---|---|---|
| 6 January – 5 April | 5 April | 3 May |
| 6 April – 5 July | 2 August | N/A |
| 6 July – 5 October | 2 November | N/A |
| 6 October – 5 January | 2 February | N/A |
Not all vehicles require reporting. Exemptions include:
- Pool cars: Vehicles shared among employees exclusively for business purposes and generally kept at the workplace.
- Disability-adapted cars: Vehicles solely used for commuting by employees with disabilities.
- Emergency vehicles: Vehicles allocated for on-call personnel in emergency services (police, fire, ambulance, paramedic) for official use only.
Personal Income Tax Band
Another critical factor in determining company car tax is the personal income tax band.
The following are the income tax bands for the financial year 2021/22:
- Basic Rate taxpayer — up to £50,270 — 20%;
- Higher Rate taxpayer — £50,271 to £150,000 — 40%;
- Additional Rate taxpayer — over £150,001 — 45%.
The higher your personal income tax band, the more tax you are liable for as company car tax. We advise that you consult or outsource a professional advisor providing tax and accounting services in the UK for detailed guidance.
Personal Contributions
Any contributions made to the car’s cost by the employee will be deducted from the final benefit in kind tax liability.
For example, the vehicle is undergoing repairs and maintenance work and remains out of use for 30 consecutive days, coupled with not having any replacement vehicle for use in the meantime. In that case, the employee’s benefit-in-kind tax will be reduced in proportion to the time they have not used the car. You can calculate the tax liabilities on your car through the HMRC Company Car Tax Calculator.
For Electric Company Car Drivers
For the 2026/27 tax year, plug-in hybrid company cars emitting 1–50 g/km of CO₂ with an electric range of 130 miles or more have a Benefit-in-Kind (BiK) rate of 4%. For hybrids with a shorter electric range, the rate varies from 7% to 16%, depending on the range. Fully electric company cars also have a BiK rate of 4% in 2026/27, rising to 5% in 2027/28.
Penalties Involved With P11D
Like other tax liabilities, there are consequences for showing negligence while filing P11D forms by employers.
In Case Of Non-Submission Or Overdue
In a non-submission case or an overdue, the offender will be charged £100 per every 50 employees, every month or part-month until the payments are made.
Incorrect Filing
A penalty is imposed based on the appropriate percentage of revenue lost, depending upon the nature of the error and the taxpayer’s guilt.
- 100% in case of a deliberate action or any fraudulent activity.
- 70% in the case of deliberate but unconcealed action.
- 30% in case of a careless mistake on the taxpayer’s part.
- 0% in case of a genuine mistake made by the taxpayer.
In Case Of Unpaid Taxes
In case of non-payment of taxes, HMRC also charges an increment of 5% of the total tax amount after a certain period has passed without any payment of taxes.
| Penalty % of the amount imposed | When paid |
| 0% | 1 – 29 days after the due date |
| 5% | 30 days after the due date (i.e. 6 Aug) |
| 10% | 6 months after the due date (i.e. 6 January following the tax year-end) |
| 15% | 12 months after the due date |
If there is an amount overdue in PAYE settlement agreements, the same penalties would apply.
Please note that no penalties would be applied if the taxpayer could present a reason deemed Reasonable by HMRC and had paid the tax as soon as they were able to. The definition of “Reasonable” in this case would differ from organisation to organisation and department, but would generally encompass unforeseen events.
Interest On Late Payment
The interest to be paid is charged on the amount that has been paid after the due date, i.e., 19 July, and is to be implemented over a period of time, allowing for the HMRC computer system stages to be upgraded.
In Case Of Cessation Of Business
If your business ceases to exist, you might be liable for Class 1A National Insurance contributions earlier than the usual due date. You are required to pay all your outstanding liabilities within 14 days, or 17 days if paying electronically, of the last tax month, or a quarter of your usual in-year payments were done quarterly, in which the final payments of ‘general earnings’ are made to an employee (Regulation 73(4) Social Security Regulations 2001). Depending upon the circumstances under which the cessation occurred, this could be earlier or even after the date of cessation due to trading purposes. The forms are rather submitted in the year rather than at the year’s end.
For Employees
The following benefits are what employees would enjoy if they opt for receiving a company car,
Financial Freedom
As an employee, most of the technicalities are taken care of by the employer, and you don’t have to worry about insurance, lease payments, or maintenance costs.
Driving Costs
Your driving costs or fuel costs are usually reimbursed or paid for by the employer, so you have nothing to worry about fuel costs when using the vehicle for business purposes.
Low BiK Rates Apply
The BiK rates charged as tax are usually only a tiny fraction of the total car’s cost. The highest BiK rate can go up to 37% of the total car cost, or 41% in the case of diesel consumption.
For Employers
Though it is one of many ways to reduce corporation tax, the following are the additional benefits an employer can receive when providing a company car
Branding Opportunities
When providing your employees with a company car, especially in the case of sales representatives, you can use your brand identity on the car and let it take part in your marketing campaigns.
Acquisition Of Assets
An employer would acquire a new company asset that can be moved over to another employee if necessary.
Attractive On Papers
The promise of providing a company car looks very attractive to potential employees and can help you secure top-of-the-line talent.
Pool Cars
What Is A Pool Car?
Note that a company car is different from pool cars provided by the company; employers are liable to pay taxes on vehicles used as pool cars. But to have the car qualify as a pool car, there are a few conditions defined by the Employment Income Manual, ITEPA 2003, s 167(3) that need to be satisfied. These conditions are as follows,
- The vehicle was made available by the employer and used by more than one employee of the company.
- The vehicle was made available to the employees due to their employment.
- The car was not used by the involved employees previously, with the exception of the others.
- Any personal use of the car made by the employee for private reasons was purely incidental towards the employee’s other uses of the vehicle. A purely incidental case would be that an employee had to travel a long distance for business purposes and had to leave early in the morning. They can take the pool car the evening before to enable themselves to get a head start on the business trip.
- The car was not kept by the employee at the residential premises of an employee overnight but can be kept in the vicinity of the residence of the one making the car available. You can consider a car is not normally kept at the employee’s residence if the total number of nights the car has stayed at the employee’s residence is less than 60% of the total time period under review.
If your car satisfies all these conditions, then it can qualify as a pool car, in which case the tax liabilities fall under the responsibility of the employer.
In Case Of Disqualification
In the case of a false claim of a pool car or false car classification, the employer may face strict penalties, including,
- A fine of up to £3,000.
- Payment of backdated company car tax for up to 4 years.
- Payment of backdated National Insurance Contributions up to 6 years.
- Penalties on late filing of these relevant taxes.
Although there are a few circumstances that require additional attention from employees as well, such as, if two or more employees are using the pool car together to commute towards work but two of them make use of the same car for their private business as well, the two employees involved in using the car for their private use would be liable for paying the full company car tax on the vehicle.
Additional Benefit: Mileage Allowance
The employees can also claim a mileage allowance and get the employer to reimburse them for fuel costs incurred while making business trips. 55p per mile for the first 10,000 miles is tax-free and can be claimed by an employee, and after the initial 10,000 miles the rate drops to 25p per mile. The 55p rate applies to mileage incurred from 6 April 2026 onwards. Earlier mileage remains subject to the previous approved rate. Additionally, the employee can claim more relief if they have another accompanying passenger for a business trip. The government allows for 5p per passenger for every mile travelled as a mileage allowance.
What Is A Car Allowance?
Another way to benefit your employees would be to equip them with a car allowance that can be added to their annual salary as a one-time increment to enable them to buy their own vehicles or lease one out. However, we advise you to read the complete guide curated by our expert accountants to get a clearer understanding of which option is right for you.
How Does Company Car Allowance Work?
A car allowance is an alternative to company cars and is provided as a one-time increment to the employee’s annual income that enables them to buy their vehicle. The employee is then responsible for using that additional amount to purchase a car, as it was intended. However, depending upon the business the recipient of the allowance is a part of, the monetary rewards can go towards the payments on an existing vehicle, the running costs, or something else entirely if they already own a car.
Although there are no hard and fast rules regarding the amounts provided as a car allowance, it depends on the employer’s amount to lease a company car. However, we have observed the rates of car allowance ranging from £150 to £1,000 a month.
Although the rates provided in each industry might differ, these amounts are taken as an average and are not standardised to base a car allowance scheme.
A requirement list for employees can also be set up that they would need to adhere to when buying a car for themselves, such as real driving emissions of CO2, the make and model of the car, etc.
Does Company Car Allowance Count As Income?
In one way or another, yes, a car allowance does count as income, as it is taxed at the source at your usual income tax rate. However, it is only a one-time payment and would only be added to your annual income for the year you are receiving the benefit.
Tax Liabilities On Car Allowance
The tax liabilities on car allowance are relatively straightforward. As it is an increment in the employee’s annual income, its tax is the same as the employee’s income tax rate. However, this implies that if they are a higher-rate taxpayer, they would have to pay a higher tax on their car allowance, as their income tax band rate would also apply to this.
For example, if you are an employee who has been granted a car allowance of £9,600, with a monthly increment of £800 for the current year. Now, as this has resulted in an increase in your income, if you are a basic rate taxpayer, you would have to pay 20% on the increased amount of £9,600 as well. If you are a higher-rate taxpayer, you would be liable for 40% of this amount as well.
If you are someone with an annual income of £45,000 and you were offered the same amount as mentioned above, you would be liable to pay a higher rate of tax as the increment of £9,600 would make you cross the threshold of the basic tax band and enter the higher tax band.
Benefits Of A Car Allowance
For Employees
Even though a car allowance means more responsibility for employees, they can still enjoy this allowance as it has its own benefits.
Freedom To Choose Your Vehicle
With a car allowance, employees get the freedom to choose a vehicle of their choice, which can prove to be a very attractive incentive for quite a lot of people.
Ownership
The employee will own the car, which can come in handy if they want to resell the vehicle to upgrade or get quick cash.
Additional Cash Injection
If they already own a car, they can use the allowance for other purposes besides buying a car.
Finding The Best Option
The employee has the freedom to choose the most suitable financing method for getting a car, such as buying or leasing.
For Employers
For some employers, a car allowance can be a lot more beneficial than providing a company car.
Reduced Responsibility
Employers will not be responsible for providing a car to their employees and will not be liable for its insurance and maintenance.
Reduced Taxes
As the car allowances are paid as a cash incentive, the employer can lower their earnings as a portion of it is given out as the allowance, hence reducing the taxes owed by them.
Payment Of Expenses
The payment of travel expenses, whether personal or business, will be the responsibility of the employee. However, the employer can provide a mileage allowance as an additional benefit if they so desire.
Tax Debate: Company Car Vs Car Allowance?
Now, to answer the question, what would be better, a company car or a car allowance?
Unfortunately, there is no “one size fits all” when it comes to this debate. Before deciding on what to opt for, there are many factors to consider. For example, if you are in a financial pinch, some might say that choosing a company car will save you from affecting your finances further. In contrast, others might think that the immediate injection of cash flow you get from a car allowance would be a better option to bring back financial stability in your life.
Ultimately, the best option for employees is the one that saves them the most money. A car allowance would be more beneficial if the employee already owns a car and is in no need of an upgrade in the near foreseeable future; however, if they belong to a higher taxpayer bracket, they might end up losing out on a lot of monetary value which they could have gotten if they had opted for a company car.
We have devised a simple solution to help you figure out what would be more beneficial to you when it comes to choosing a company car or car allowance. To do this, find out the monthly allocation you would get if you opted for the car allowance program. Deduct any income tax and national insurance contributions from the sum and assess if the excess amount is enough to cover your additional commuting expenses such as insurance, repairs and depreciation. If so, then opting for a car allowance would be the most beneficial for you.
How Can a Car Allowance Save Money For An Employee?
Suppose you are currently driving a Mondeo 1.6 TDCi Zetec, but you are looking to upgrade from the current model to something more your style, like the BMW 3 Series. You bring it to your company’s attention, and after assessing your records, the director decides to provide you with a car allowance of £500 per month to upgrade your car.
Now you get to thinking and are required to do some calculations,
Calculations
Suppose you are a higher-rate taxpayer for the 2026/27 tax year and currently pay £145 per month in BiK tax on your Mondeo. For this example, assume that this is the monthly BiK tax you would save by giving up the company car.
If your employer provides a car allowance of £500 per month, you would lose £210 to Income Tax and National Insurance, leaving a spendable allowance of £290 per month. Adding the assumed £145 monthly BiK tax saving gives you a total monthly budget of £435 for your car upgrade.
Consider leasing out the vehicle at 12,000 miles per annum, including maintenance and go around looking for quotations. You find a supplier willing to lease out the car to you at £330 per month, including repair and servicing, so your tyres and maintenance are covered. You also decide to get your vehicle insured for £600, adding £50 to your monthly liability.
After comparing the engines and fuel consumption of your new and previous car, you will find out that you’d be burning through an extra fuel tank in a month with the new car, which adds a total of £65 to your monthly expenses.
Looking at past statistics, you can assume that you travel 150 miles per month for business. For mileage incurred from 6 April 2026 onwards, you can claim at the approved rate of 55p per mile, giving a total mileage allowance of £82.50.
The new 55p rate applies to mileage incurred from 6 April 2026 onwards. Earlier mileage remains subject to the previously approved rate.
Final Calculations
Now, the final calculation would come out to be,
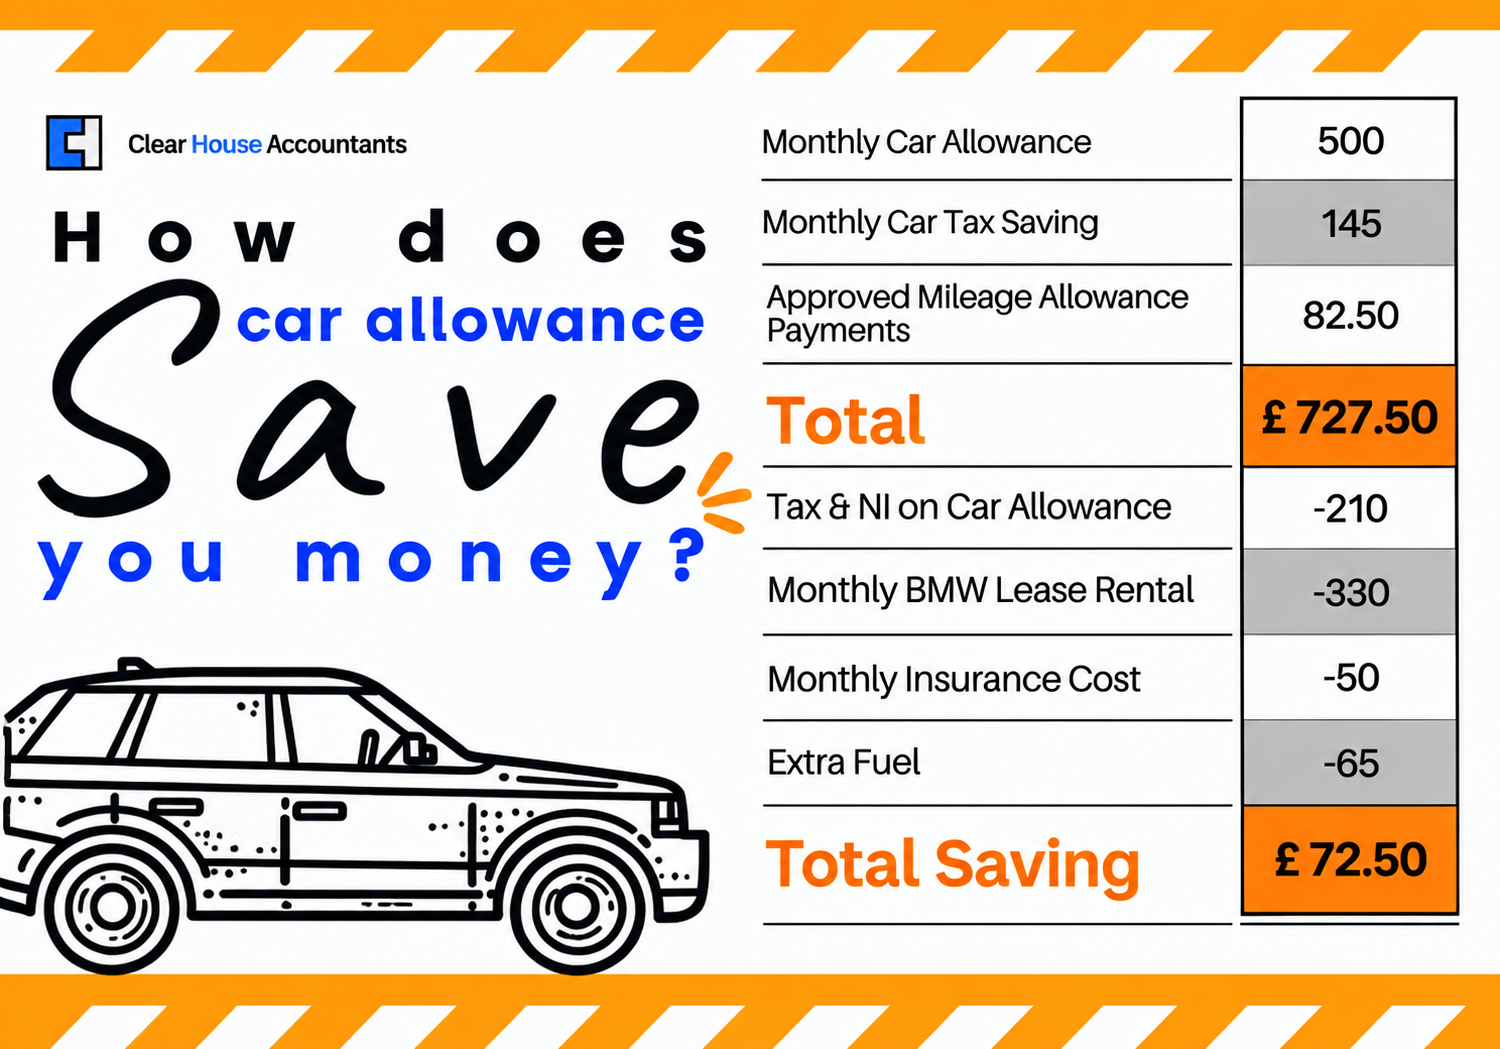
As you can see from the above example, after taking out all possible deductions and expenses, you are left with £72.50, which is the additional benefit you would be getting because you opted for the company car allowance over the company car. This is a significant difference.
This is why it is strongly recommended that you look for advice from skilled professionals to help you decide the most suitable course of action for yourself or your business.
Conclusion
Ultimately, whether you opt for a company car or decide to take on the car allowance depends entirely on your financial position, preferences, and requirements. However, we can safely assume that a company car and its tax liability carry their merits and demerits. But, as far as the tax liability is concerned, people tend to choose options that save them the most money. Hence, car allowances are a better choice, and with more businesses offering cash alternatives to company cars, it seems like they understand that as well.
But if you still have any uncertainties regarding the best option for you, look for advice from professional accountants or tax services that would help you find exactly what you are looking for.
Additional Resources